Japan’s policy rate reaches a 31-year high
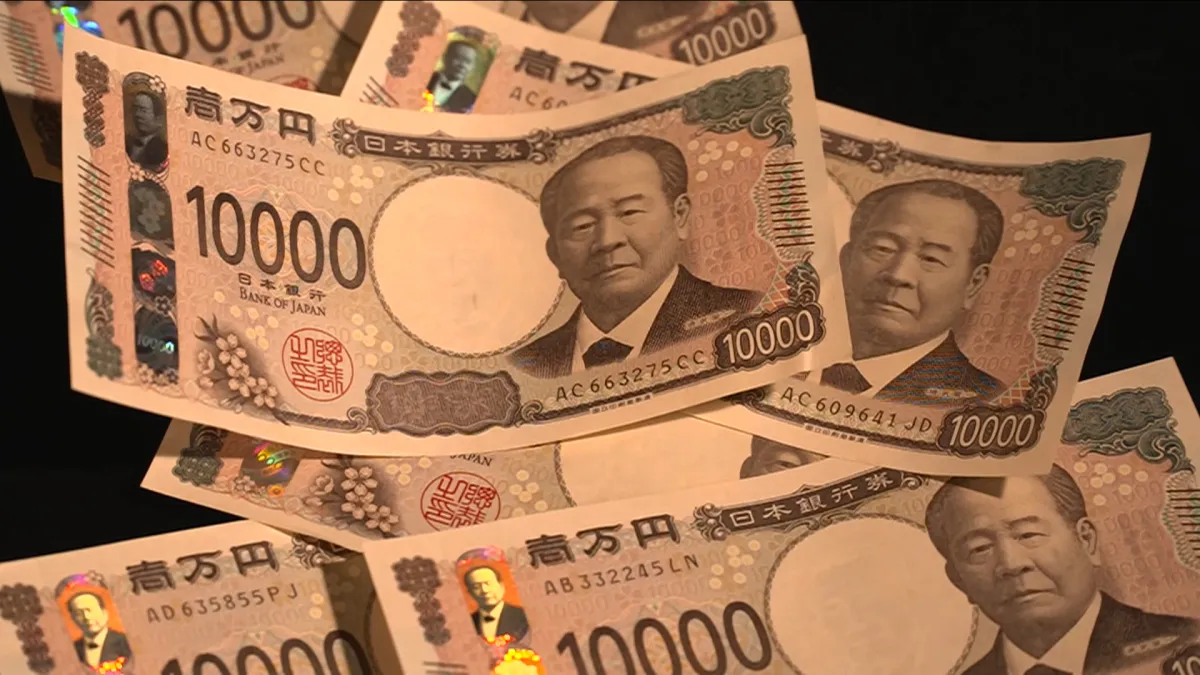
The Bank of Japan decided on September 18 to raise its policy interest rate from around 1.0% to approximately 1.25%, marking the highest level since 1995. The increase is the second rate hike of the year and comes only three months after the previous adjustment—an unusually rapid pace for Japan, where borrowing costs remained extremely low for many years.
The central bank’s decision reflects growing concern that inflationary pressures could become more persistent. Rising crude oil prices linked to tensions in the Middle East are adding to costs, while strong demand connected to artificial intelligence is supporting activity in parts of the global economy. For the Bank of Japan, raising rates is one way to moderate demand and prevent price increases from becoming entrenched.
Higher rates will not immediately lower prices
Although the move is intended to help control inflation, consumers should not expect prices to fall immediately. According to a survey by Teikoku Databank, 4,923 food and household items were scheduled for price increases in September—the highest monthly total so far this year. More than 3,000 additional items are also expected to become more expensive in October.
Interest-rate increases can eventually help stabilize the economy, but they also create short-term challenges. Higher rates may improve returns on bank deposits, offering some benefit to savers. At the same time, they can increase borrowing costs, discourage spending and place additional pressure on businesses and households.
Mortgage borrowers face a direct impact
The effect is particularly significant for people with variable-rate home loans. An estimate by Mizuho Research & Technologies suggests that annual repayments could rise by approximately 50,000 yen for households where the borrower is in their 20s or younger, 41,000 yen for those in their 30s, and 28,000 yen for borrowers in their 40s.
These figures are estimates, and the precise impact will depend on each loan’s terms, including its interest-rate review schedule and repayment rules. Nevertheless, the prospect of rising monthly costs is already influencing housing decisions. One person in their 30s said they were considering buying a home but had become hesitant because of higher rates. Another said renting seemed more realistic because purchasing a home felt unaffordable. For younger people in Japan, where housing costs and other living expenses are already major concerns, the decision between renting and buying is becoming even more complicated.
Why “effortless saving” may be more sustainable
Financial planner Aya Furouchi recommends beginning with fixed expenses rather than making severe cuts to everyday necessities. Reviewing mobile-phone and internet providers, cancelling unused streaming or subscription services, and reassessing insurance coverage can produce meaningful savings after a single review.
These tasks are often postponed because they require time and paperwork. A long weekend or holiday period, such as Japan’s September Silver Week, can provide a useful opportunity to examine recurring payments and remove services that no longer offer sufficient value.
By contrast, households should be cautious about cutting food costs too aggressively. Reducing meal portions or lowering food quality may be difficult to maintain and can lead to a later spending rebound. A large “reward” meal after an exhausting period of restriction may cancel out the intended savings. Starting with fixed costs, while protecting essential food spending, offers a more balanced and sustainable approach.
A changing financial environment in Japan
For foreign residents, the policy shift is an important reminder to check how Japanese interest rates affect mortgages, bank savings, remittances and household budgets. Anyone considering a home purchase should compare variable and fixed-rate products carefully and seek advice based on their own income and repayment capacity. The Bank of Japan’s move signals a changing era for Japan’s economy—one in which modest interest income may return, but borrowing and daily financial planning require greater attention.